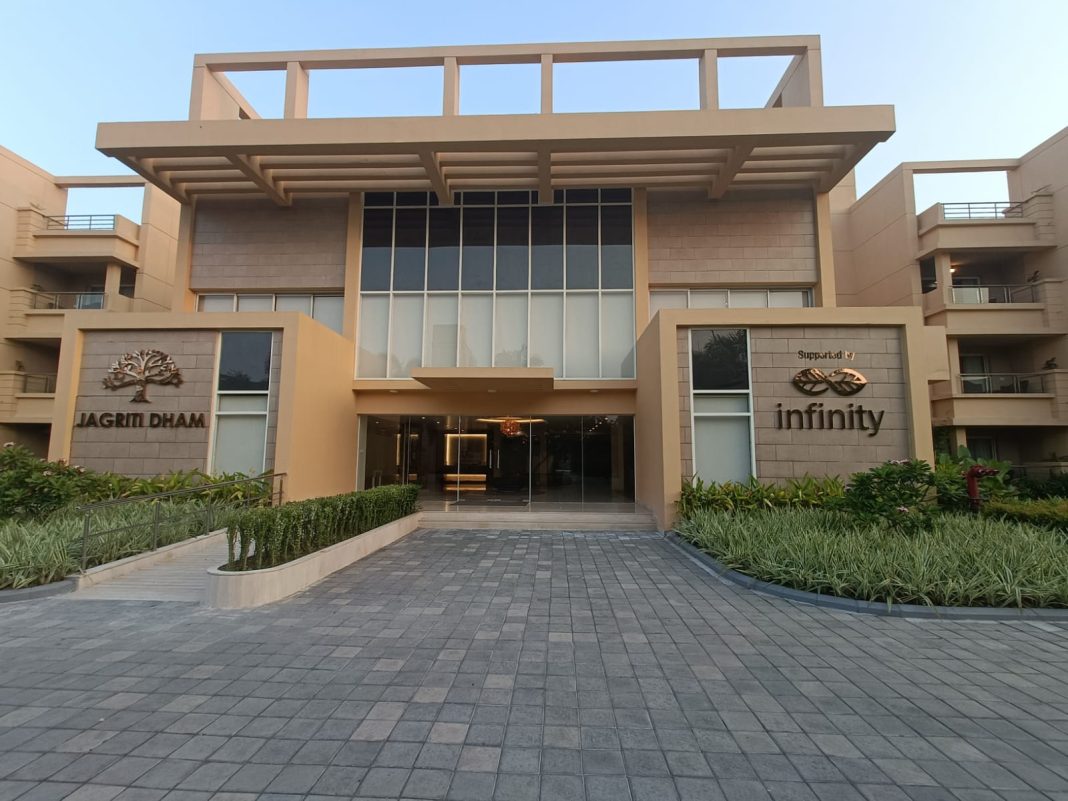

Senior citizens in India can save more tax legally through seven specific strategies — investing in SCSS to claim Section 80C and generate higher-rate sovereign income simultaneously, claiming Section 80D on medical insurance, claiming Section 80TTB on interest income, submitting Form 15H to prevent unnecessary TDS, choosing the old tax regime where deductions produce more savings, using the higher exemption limit to plan income below the threshold, and filing the annual return to reclaim any TDS deducted above actual liability. At Jagriti Dham by Infinity Group near Joka, Amtala, residents live in the best senior living in india community. Here, all seven strategies are implemented as a standard administrative service.
Legal tax saving for senior citizens in India is not tax avoidance — it is the complete, correct use of the government’s own provisions for older adults. Every provision described in this guide is built into the Income Tax Act specifically for senior citizens — and every rupee of tax saved through these provisions is a rupee the government intended seniors to keep. Understanding which strategies produce the most saving for a specific income profile is what converts general knowledge into actual benefit. Residents at the best senior living in india facility like Jagriti Dham near Joka receive exactly this income-specific strategy guidance from the administrative team every year.
Legal Tax-Saving Strategies for Senior Citizens in India — Each One Specific, Actionable, and Available Under the Existing Income Tax Framework
The seven strategies below are each immediately actionable — and each produces a specific, quantifiable tax saving:
Invest in SCSS to claim Section 80C and earn the highest safe rate simultaneously. SCSS investment up to Rs 1.5 lakh claims the full Section 80C deduction while generating 8.2 per cent annual interest income — making it the only instrument that simultaneously reduces tax liability and produces the highest available government-backed return. The senior luxury living administrative team at Jagriti Dham opens SCSS accounts for every eligible resident and ensures the Section 80C claim reflects the correct investment amount in the annual return.
Claim Section 80D on medical insurance premiums or medical expenditure. Senior citizens who hold medical insurance should claim the full Section 80D deduction of up to Rs 50,000 on premiums paid. Where no insurance is held, the same limit can be claimed on actual medical expenditure. At the 20 per cent slab, the maximum Section 80D saving is Rs 10,000 annually. The assisted living senior care administrative provision at Jagriti Dham documents both insurance premiums and medical expenditure for every resident to ensure the higher-value basis is always claimed.
Claim Section 80TTB to deduct up to Rs 50,000 of interest income. Section 80TTB allows senior citizens to deduct up to Rs 50,000 of interest income from savings accounts, FDs, and RDs — and the Budget 2025 increase of the TDS threshold to Rs 1 lakh under Section 194A reduces automatic TDS deductions for most senior FD and SCSS holders. The Jagriti Dham administrative team at Jagriti Dham claims Section 80TTB for every resident with eligible interest income and advises on structuring interest income to maximise the deduction benefit.
Submit Form 15H at the start of each financial year to prevent TDS. For senior citizens whose total annual income is below the taxable threshold, submitting Form 15H to the SCSS institution, bank, and post office in April prevents TDS deduction on interest income — avoiding the need to file for a refund at year-end. The luxury retirement homes India administrative team at Jagriti Dham submits Form 15H for every eligible resident in the first week of April.
Choose the old tax regime where deductions produce more saving than the flat rate. The old regime’s higher exemption limits and deduction framework produces more tax saving than the new regime’s flat rates for most seniors with significant SCSS, Section 80D, and Section 80TTB deductions. The senior care assisted living financial guidance at Jagriti Dham compares both regimes annually for every resident — recommending the one that produces the lower tax liability for their specific income and deduction profile.
Plan total annual income to stay below the applicable exemption threshold. A senior whose total income — pension, SCSS interest, rental income — is below Rs 3 lakh (or Rs 5 lakh for those aged 80 and above) has no tax liability. For seniors close to the threshold, timing decisions — deferring a rental receipt or investing in Section 80C instruments — can eliminate liability. The senior care facility at Jagriti Dham reviews each resident’s income position by December to identify threshold-management actions before March.
File the annual income tax return to reclaim any TDS deducted above actual liability. Many senior citizens do not file an annual income tax return because they believe their income is too low — but this is precisely when filing is most valuable: to reclaim the TDS that institutions deducted above the senior’s actual liability. A resident whose total annual income is Rs 2.8 lakh but who had Rs 3,000 of TDS deducted on FD interest can reclaim the full Rs 3,000 through filing. The assisted living senior care at Jagriti Dham files annual returns for every resident where TDS has been deducted and the return would produce a refund. Families can review the full service at the senior care assisted living listing — where the administrative and financial guidance standard at Jagriti Dham is described.
How the Best Senior Living in India at Jagriti Dham Implements All Seven as a Standard Residential Service
The seven strategies are implemented through a coordinated annual cycle at Jagriti Dham:
- April Form 15H submission
- Mid-year income review
- December threshold assessment
- Annual return filing that reclaims any excess TDS
The administrative team manages every step for every resident — and the family receives confirmation of each action and its outcome. The senior care facility standard at Jagriti Dham makes legal tax saving a residential provision — not a task the resident or family must remember, commission separately, or manage remotely from abroad. Families can review the full service at the senior care assisted living listing — where the administrative and financial guidance standard at Jagriti Dham is described.
Seven Strategies Fully Implemented: Effortless Legal Tax Saving at Jagriti Dham
Legal tax saving for senior citizens in India is not complex — it is seven specific strategies, implemented in the right sequence at the right time of year, producing the maximum after-tax income from the same gross income. Residents at the best senior living in india community at Jagriti Dham by Infinity Group near Joka, Amtala, receive all seven strategies as a standard annual service — so that every eligible provision is claimed and no tax is paid that the government did not intend seniors to pay.
Frequently Asked Questions
Q1. What is the best way to combine tax-saving strategies under the old regime for a senior at Jagriti Dham with a total annual income of Rs 3.2 lakh (Rs 2,46,000 in SCSS interest and Rs 74,000 in pension)?
With Rs 3.2 lakh total income, this senior exceeds the Rs 3 lakh exemption by Rs 20,000. The most effective strategy is to apply the standard deduction of Rs 50,000 on pension income — reducing total taxable income to Rs 2.7 lakh, below the threshold. This eliminates tax liability entirely. Section 80TTB additionally deducts up to Rs 50,000 of SCSS interest, reinforcing the below-threshold position. Form 15H is then submitted to both the SCSS institution and the pension bank to prevent TDS. The Jagriti Dham team implements all three steps in the correct sequence.
Q2. For a super senior citizen at Jagriti Dham aged 81 with income of Rs 6.2 lakh, which strategies produce the greatest tax saving under the old regime?
With Rs 6.2 lakh, a super senior aged 81 faces tax on Rs 1.2 lakh above the Rs 5 lakh exemption — at 20 per cent, producing Rs 24,000 (plus cess). Section 80TTB for Rs 50,000 interest deduction brings tax to Rs 14,000. Adding Section 80D for Rs 30,000 in premiums brings tax to Rs 8,000. Adding Section 80C for Rs 1.5 lakh SCSS investment brings taxable income to Rs 3.9 lakh — below the Rs 5 lakh threshold, eliminating tax liability. The Jagriti Dham team applies all three deductions in this sequence annually.
Want to implement all seven tax-saving strategies for your parent at Jagriti Dham near Joka?
Book a scheduled visit — ask the administrative team how the annual tax strategy cycle works for residents.
About Jagriti Dham
This guide was curated by the Jagriti Dham team (www.jagritidham.com). Jagriti Dham is Kolkata’s most luxurious senior citizen home and Eastern India’s first Indian Green Building Council-certified green senior living facility, situated near Joka, Amtala in South Kolkata. A project of the Infinity Group, Jagriti Dham is envisioned as a centre of excellence, promoting active ageing and aiming to build an age-integrated society — where elders can live independently while receiving the best possible care. Unlike other old age homes, Jagriti Dham’s vision extends beyond the walls, giving elders a hassle-free life in a peaceful, like-minded community.
Follow us: Facebook | YouTube | Google My Business | LinkedIn | Instagram